Wednesday, April 2, 2025

For The Archives -- Liberation Day -- April 2, 2025

Locator: 48408B.

Liberation Day: for the archives.

And here I thought the world was coming to an end, link here.

SIR: this LDC story is getting wilder and wilder by the day. More later.

Big stories now being followed:

  • America's sixth industrial revolution (SIR): chips, LCDs, and energy infrastructure
  • LDC -- huge energy drain; huge buyer of ARM-based CPUs, Nvidia GPUs
  • US universities under attack: Columbia, Harvard, Princeton
  • US natural gas exports: hits record; it's now being reported that Permian natural gas takeaway -- despite huge build -- has now reached capacity -- see RBN Energy;
  • Mideast: is the air war on Yemen just a warm-up? Iran wants to know
  • the EV story -- how far have protestors set back the EV story? Does it have legs? 
    • folks seem to forget that most EVs sold in America re-charge using Tesla charge points when away from home; just one more concern for folks thinking about buying any EV
    • Rivian: incredibly bad quarter; tries to put positive spin on 1Q25 results; link here;
    • Tesla: hard to say if worse than expected; Tesla has become a moving "target" -- literally and figuratively
  • tariffs (of course, for the archives; hopefully I will ignore most of this nonsense; others will cover)
    • Canada just blinked: said it will "remove tariffs if the US does the same" -- Evan.
  • the big political story yesterday, under-reported -- photo ID required for voting in Wisconsin.

Political story: has the Pete Hegseth story died? Mike Waltz with another embarrassing data security failure (used Gmail for official work).  

************************************
Back to the Bakken

WTI: $70.93.

New wells:

  • Thursday, April 3, 2025: 14 for the month, 14 for the quarter, 211 for the year,
    • 41019, conf, CLR, Bud FIU 6-30H,
    • 40883, conf, Murex, LA-Jean Claudine 25-36H MB,
    • 40371, conf, Slawson, Kahuna 4-6-7H,
    • 40150, conf, CLR, Marshall 3-24H,
    • 39812, conf, Kraken, Apollo 18-7-6 2H,
    • 39694, conf, Hess, TI-Beauty Valley-158-95-1423H-7,
    • 39040, conf, Grayson Mill, Orville 4-9 XW 1H,
  • Wednesday, April 2, 2025: 7 for the month, 7 for the quarter, 204 for the year,
    • 41033, conf, BR, Cleetwood 7C,
    • 40223, conf, Slawson, Kahuna 5-6-7H,
    • 39813, conf, Kraken, Apollo 18-7-6 1H,
    • 36620, conf, BR, West Kellogg 2C-MBH, 

RBN Energy: are you kidding me! Is the Permian Basin already out of natural gas takeaway capacity? Archived.

After a record run of negative pricing last spring and summer, the Permian Basin collectively cheered as WhiteWater’s Matterhorn Express pipeline began flowing last October, bringing much-needed takeaway capacity to the area. Cash prices at the Waha Hub rebounded and the basin had a relatively uneventful winter, but prices began dropping in early March and have once again traded below zero for most of the past two weeks. This has taken the market somewhat by surprise, as many expected the impact of Matterhorn’s startup to last more than a few months. In today’s RBN blog, we’ll look at what’s driving the recent run of negative pricing in the Permian Basin and what it means until additional infrastructure comes online next year. 

Permian gas supply has exploded, growing by 11.5 Bcf/d since the beginning of 2019. But as the prolific basin has expanded, it has outgrown the area’s natural gas infrastructure. Producers in the basin, unlike in most other supply areas, are willing to tolerate extremely low and even negative gas prices. Why? Because that’s not how they make money. The Permian is associated gas production, so as long as the oil price is favorable, the gas will keep coming, regardless of how low cash prices go. And it’s important to note that most of the big producers have firm capacity out of the Permian, so they are not exposed to negative prices. It’s mostly the smaller producers that feel the pain.

Before getting into the details, we need to point out that this analysis is based on RBN’s new Arrow Model product, which is now available for our subscription customers. The model (1) aggregates gas production, demand and net outflows or inflows for each market hub over time; (2) quantifies the degree to which gas is pushed/pulled between and among hubs, again over time; (3) anticipates gas flows on each corridor (and the need for incremental pipeline capacity); and (4) forecasts the basis differentials that underlie and support the aforementioned flows of gas. For more information, click here.

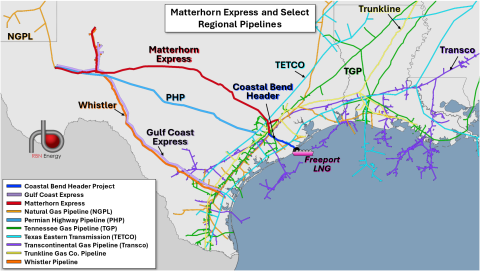
Now back to our analysis. Because of its location in West Texas and New Mexico, there is very little local demand within the Permian itself, so nearly all the gas produced must be piped elsewhere. Pipelines take the gas in four basic directions: west toward California, north to the Midcontinent, south to Mexico, and east toward the Gulf Coast and South Texas markets. Outflows east began with legacy capacity on a number of Texas intrastate pipelines, but this route has become increasingly popular due to exploding feedgas demand from LNG export terminals along the Gulf Coast. Since 2019, four new greenfield pipelines have come online to move gas out of the Waha area in this direction. Gulf Coast Express (lavender line in Figure 1 below) and Whistler Pipeline (dark-orange line) take a combined 4.5 Bcf/d to the Agua Dulce area, and Permian Highway Pipeline (PHP; medium-blue line) and the newest addition, Matterhorn Express (red line), target the Katy area near Houston. Permian Highway has a capacity of 2.5 Bcf/d thanks to a compression expansion on the pipeline in 2023. Matterhorn has or will have a capacity of 2.5 Bcf/d, but whether all of that capacity is online and available is one of the biggest questions lingering as the market grapples with this latest run of negative Waha prices.
Matterhorn Express and Select Regional Pipelines  

Figure 1. Matterhorn Express and Select Regional Pipelines. Source: RBN 
Tuesday, April 1, 2025

Oh, My Goodness -- Say It An't So -- Val Kilmer Dies -- Age 65 -- April 1, 2025

Locator: 48407KILMER.

NYT obituary. 

Cause: pneumonia.

Prior: diagnosed with throat cancer in 2014; recovered. Obviously survived the Covid scare. 

Another movie, like Dr Zhivago, I can never watch again -- Top Gun -- way too sad for me to watch. A handful of movies had a huge effect on me. Top Gun was one of those movies. That movie came out while I was assigned to an F-15 squadron in Germany. 1986. Seems like yesterday.

Interestingly, one might think Casablanca would fall into that category, but I never get tired of Casablanca. 

Obituary by Bruce Weber.

***********************
The Book Page

Tonight:

Chart Of The Day -- April 1, 2025

Locator: 48406ARCHIVES.

Chart of the day: because this is April 1st, we may want to check back in, let's say in 24 hours to see if this is truly accurate. (It is.) Link here. Now, valued more than Reddit. Shortly after the market close it was up another $15 but then later, was down a bit.

Five days:


 ******************************
Meanwhile

Politics: the WSJ called it a "closer-than-expected" race but the fact is the winner won by a landslide. Despite very, very low voter turnout in a solidly red district. 

Politics: the GOP had a chance to change things, but then they screwed things up. Google Anna Paulina Luna for the story. Now watch the President continue to run the country by executive order and the shadow president, Judge Jim, fight him at every step. But if I get discouraged, I just watch this video.

Apple Card, link here:

********************
Quite A Market
ATT

Link here. 

Five New Permits -- April 1, 2025

Locator: 48405B.

The dot chart, link here. 

Looks like a record high (demand) -- in the chart below --  just when it's being reported that American crude oil production has hit an 11-month low. Wow, that production metric: completely wrong on so many levels. We posted this yesterday with regard to US crude oil production. US crude oil production set a new all-time January record; twelfth consecutive month above 13.1 million bopd, field production. Link here.
Folks are concerned about shale oil production dropping / declining: let's see what WTI does if WTI were to hit $100. That solid dark green line in the graphic below? The year before Covid-19 lockdown, 2019. The month I'm watching: August. Will the US set a new all-time record?

*******************************
Back to the Bakken

WTI: $70.21.

Active rigs: 35.

Five new permits, #41759 - #41763, inclusive:

  • Operators: KODA Resoures (4); Denbury Onshore;
  • Fields: Fertile Valley (Divide County); a wildcat in Bowman County;
  • Comments:
    • Denbury Onshore has a permit for a CHSU well, SWSW 20-131-105, Bowman County, a wildcat, 
      • to be sited 351 FSL and 1002 FWL:
    • KODA Resources has permits for four Amber wells, Divide County, NENW 22-160-103; 
      • to be sited 400 FNL and 2433 / 2538 FWL.

Changes:

  • 39741, Grayson Mill, Darlene 13-24F 4H; spacing changed from four-section to two sections.

Three producing wells (DUCs) reported as completed:

  • 40565, 1,322, Neptune Operating, Simpson 5-8 6H, McKenzie County;
  • 40587, 1,378, Neptune Operating, Simpson LW 5-8 12H, McKenzie County;
  • 40588, 1,191, Neptune Operating, Simpson 5-8 5H, McKenzie County;

Tuesday -- April 1, 2025

Locator: 48404B.

Inflation watch: 2-liter Diet Coke. The best I can do at Walmart is $2.79. Target generally runs about $3.29. Today, at our local big box beverage store, three for $7,00 or $2.33 / 2-liter bottle.  Even without the "special" today they have prices that meet or beat Walmart's price for Coke products. 

Tariffs: I assume the $11.99 I spent for a bottle of German white wine today will be significantly more expensive a few weeks from now. Regardless, $11.99 for a bottle of German white wine is probably less expensive than what it would cost me in Germany.

The Boasberg orders: illegal. Link to WSJ.  

Must-watch US Navy in action. One might ask, "who is the intended audience?" It ain't the American public.

.
Then, one might want to read this individual's resume: Sunita Williams.

***********************************
Back to the Bakken

WTI: $71.51.

New wells:

  • Wednesday, April 2, 2025: 7 for the month, 7 for the quarter, 204 for the year,
    • 41033, conf, BR, Cleetwood 7C,
    • 40223, conf, Slawson, Kahuna 5-6-7H,
    • 39813, conf, Kraken, Apollo 18-7-6 1H,
    • 36620, conf, BR, West Kellogg 2C-MBH,
  • Tuesday, April 1, 2025: 3 for the month, 3 for the quarter, 200 for the year,
    • 41186, conf, Murex, LA-Emma Rose 30-31H LE MB,
    • 40154, conf, Hess, EN-Engebretson-157-94-1003H-4,
    • 39320, conf, Grayson Mill, Marilyn 31-33 4H,

    RBN Energy: Enterprise's plan to return to ECHO 2 to crude service can't come soon enough. Archived.

    As crude oil pipelines from the Permian to the Gulf Coast edge closer to full utilization, it’s becoming a challenge for producers and shippers alike. Amid this capacity crunch, converting Enterprise’s Midland to ECHO 2 (M2E-2) pipeline back to crude oil service can’t come quickly enough. In today’s RBN blog — the latest in our series on Permian crude oil pipelines — we discuss Enterprise’s crude oil footprint from West Texas to Houston. 

    In Part 1 and Part 3 of this series, we looked at the Longhorn and BridgeTex pipelines, respectively, and what ONEOK has accomplished with these systems since it acquired Magellan Midstream in 2023 (see Tulsa Time). In Part 2 and Part 4, we looked at the EPIC Crude and Gray Oak pipelines, respectively, to the Corpus Christi area, which have both been operating at full capacity. Today, we’ll cover Enterprise’s Midland to ECHO (M2E) pipelines. 

    Enterprise has two major oil pipelines from the Permian to the Gulf Coast — soon to be three (again)! To the Houston area, the long-hauls include the company’s Midland to ECHO 1 (M2E-1, pink line in Figure 1 below) and Midland to ECHO 3 (M2E-3, which represents the company’s 29% undivided interest in the Wink to Webster — or W2W — system shown in orange). Together, these give Enterprise 1.07 MMb/d of crude takeaway capacity. Further, Enterprise’s Midland to ECHO 2 (M2E-2; blue line) will soon be returned to crude oil service. (More on that in a moment.) M2E-1 and M2E-2 twin each other (meaning they follow the same path), originating at Midland and flowing to Sealy (black dot west of ECHO). Then, at Sealy, M2E-1 and M2E-2 utilize Enterprise’s Rancho II pipeline (green line) to its ECHO terminal (pink tank icon). While the ExxonMobil-operated W2W follows the same path for a portion of the line, it flows from Midland directly to ECHO, bypassing Sealy and the Rancho II line. (Enterprise is also a non-operating JV partner in Basin Pipeline from the Permian to Cushing, which we’ll discuss in a future blog.)

    Enterprise Permian Outbound Crude Oil Long-Haul Pipelines

    Figure 1. Enterprise Permian Outbound Crude Oil Long-Haul Pipelines. Source: RBN