Locator: 50979INFRASTRUCTURE.

Somehow there seems to be a connection between the above and the below:


Locator: 50979INFRASTRUCTURE.

Locator: 50978MARKET.
Tag: Paramount, Ellison,
 BRKB will open down:

Gravitas:

UFC: gravitas-er


Did the Trump administration favor the Paramount - WBD deal?


The most important word in that reply? Oracle.


I'm sure there will be more throughout today.
Locator: 50977B.
Anticipation:

*************************************
Back to the Bakken
WTi: $80.58.
New wells reporting:
RBN Energy: several northeast gas pipeline projects focus on Pennsylvania, regional enhancements. Link here. Archived.
Demand for natural gas is rising both within the U.S. Northeast and in regions to its south and west. That incremental demand is spurring the development of a host of gas pipeline projects — small, medium and large — that collectively will enable Marcellus/Utica E&Ps to ratchet up their production year by year well into the 2030s. In today’s RBN blog, we continue our analysis of the new pipelines and pipeline expansions being planned to move more gas within — and out of — the U.S.’s largest gas production region.
This is the fourth blog in a series about gas market dynamics in the Northeast. In Part 1, we said that while the dramatic changes happening in Texas and Louisiana have garnered the most attention in the past year or two, the Appalachia market has been quietly evolving in ways that will not only shift flow patterns within the region but also affect flows to the Southeast, Midwest and Gulf Coast. Part 2 focused on gas demand within the Northeast, which is getting a big boost from the power-generation sector as coal retirements continue and data center development proliferates. In Part 3, we started a review of the pipeline projects being planned to enable more gas to flow through and out of the Marcellus/Utica to existing and new demand centers, focusing on projects in New England and New York.
Today, we continue that review. There’s no simple way to categorize most of the remaining projects. The best we can do is separate them into these five buckets: (1) projects within Pennsylvania; (2) regionwide enhancements; (3) projects tied to Mountain Valley Pipeline (MVP) and Transco; (4) expanded capacity to Ohio and beyond; and (5) projects that are more distant but still related to the Marcellus/Utica.
Projects within Pennsylvania
We’ll start with National Fuel Gas Co. (NFG), which is building two gas pipeline projects in the Keystone State and planning another. NFG is not familiar to everyone, so we should note that it is an integrated energy company that produces natural gas in north-central and northwestern Pennsylvania, owns and operates a gas pipeline network — National Fuel Gas Pipeline (NFGP; lime-green lines in Figure 1 below) — and the Empire Pipeline (magenta lines) and distributes gas to retail customers in northwestern Pennsylvania and western New York.
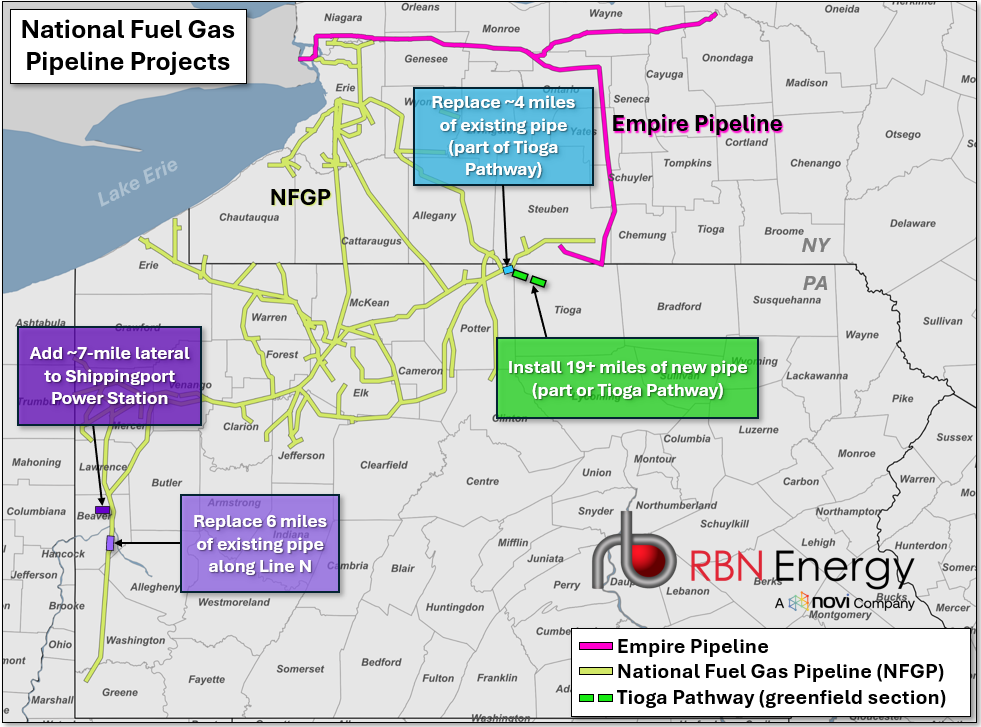
Figure 1. National Fuel Gas Pipeline Projects. Source: Novi Labs
Locator: 50976COMPUTERS.
Tag Apple AAPL Dell Raptor Lake
Comparable products (Dell / Intel Raptor Lake vs Apple Mac): Apple can beat on price with better product (though this will be affected by a) eye of the beholder; and, b) options / incentives provided by manufacturer / seller.
Intel's Raptor Lake: link here.

Query:
Top Apple Mac. How many cores; how does this compare with Intel's Raptor Lake topping out at 20 cores?
Reply:
From the linked article:
Yesterday, we broke news of a third Raptor Lake refresh in the works from Intel, dubbed "Raptor Lake Next."
Following that, new leaks have emerged from reliable tipster Jaykihn confirming the codename and detailing the upcoming family. Raptor Lake Next is slated for early 2027 and will land on the LGA 1700 socket as reported previously, but some outlets say it will also retain the existing Core 200 branding.
Comparable Macs are already being sold. But we will have to wait for "official" reviews.
Locator: 50975COLA.
Updates
From June 12, 2026, from CNBC (same numbers but different story), link here: 3.8% for 4.7% COLA for social security recipients.
Original Post
From June 10, 2026:
****************************
Social Security
Maybe it might be time to end COLAs for social security.
But until we do ...

I talked about his offline with a reader some weeks ago ... this is a bigger deal than folks might realize. This is going to affect military raises and pensions also.
The best the active duty military ever did in the past 30 years was 5.2% in 2024. The second best was 2023, 4.6%.
But look at this: larger percentage raises occurred in the early 1980s (peaking at 14.3% in 1982) at which time I was a senior officer on active duty.
In many respects, many social security recipients need the COLAs the least of all socio-economic groups.


