Wednesday, September 20, 2023

Holy Mackerel: My Favorite Chart -- Another Huge Spike -- From Where Is All This Money Coming? September 20, 2023

Locator: 45514INV.

Updates

September 22, 2023: And it looks like it is not going to quit any time soon. I remember when I first started this series, "my favorite chhart," a reader suggested I knew nothing about investing, which is probably true, but it's interesting how this chart has become pretty interesting in its own right. 

Anyway, from a a different reader, this link.

Original Post

From where is all this money coming? Some would say they are printing it. My hunch, three sources:

  • from under American mattresses;
  • Europe;
  • China.

Goldilocks economy.

My favorite chart.

Link here.


From earlier:

Link at twitter.

New Developments In Bakken Crude Oil Production and Dakota Access Pipeline Drama -- RBN Energy -- September 20, 2023

Locator: 45513B.

RBN Energy: new developments in Bakken crude oil production and DAPL. Archived.

A draft environmental impact statement (DEIS) tied to a key water crossing along the Dakota Access Pipeline (DAPL) has finally been completed and made public, thereby ending another chapter in the long-running drama about the ultimate fate of DAPL, which is by far the largest crude oil pipeline out of the Bakken. While the DEIS doesn’t finish the story, the document provides hints about possible outcomes — and an opportunity to review just how important the 750-Mb/d pipeline really is to Bakken producers and shippers. In today’s RBN blog, we discuss the latest developments regarding DAPL and Bakken production. 

More than 10 years ago, in Express Yourself (Dakota), we blogged about Koch Industries’ plan to help pipe crude oil all the way from western North Dakota to the Gulf Coast. The plan was complicated. It called for the development of the 250-Mb/d Dakota Express — a combination of new and repurposed Koch pipe from the Bakken to the crude hub in Patoka, IL (via Minneapolis) — and a possible connection from Patoka to Energy Transfer’s proposed Eastern Gulf Crude Access Pipeline (EGCAP), which involved the repurposing of the Trunkline natural gas pipeline to St. James, LA, and maybe a run of new pipe from there to the Louisiana Offshore Oil Port’s (LOOP) onshore storage hub in Clovelly, LA.

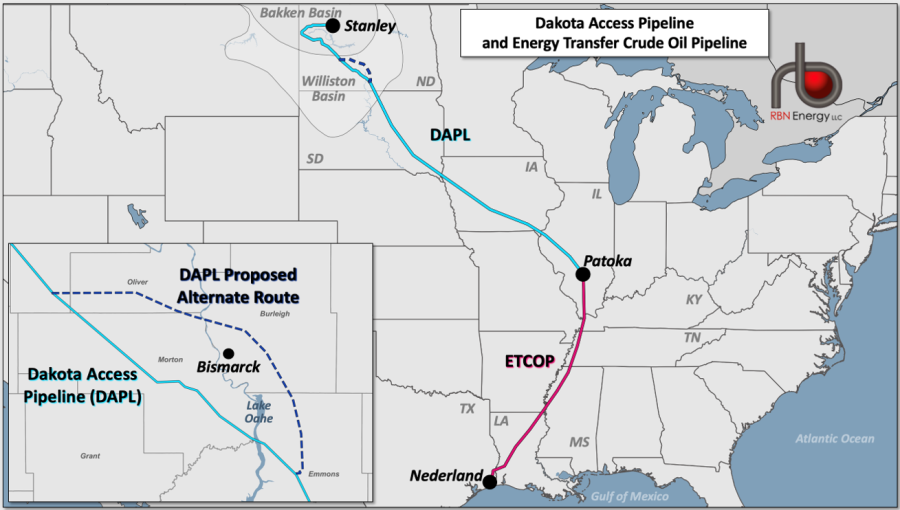
New takeaway capacity out of the Bakken was desperately needed — production in the shale play (aka the Williston Basin) was growing by leaps and bounds through the first half of the 2010s, forcing many shippers to resort to more expensive crude-by-rail. Koch’s proposed Bakken-to-Patoka link never happened and was later replaced by DAPL (light blue line in Figure 1 map and inset), which came online in June 2017 as a 470-Mb/d facility (see What a Difference a DAPL Makes). EGCAP morphed into ETCOP (Energy Transfer Crude Oil Pipeline; red line in map), which terminated at Nederland, TX, (not St. James) and started up the same month. DAPL and ETCOP are collectively known as the Bakken Pipeline System and are co-owned by Energy Transfer (with a ~36% share), Enbridge (~28%), Phillips 66 Partners (25%), MPLX (~9%), and ExxonMobil (~2%).

Dakota Access Pipeline and Energy Transfer Crude Oil Pipeline

Figure 1. Dakota Access Pipeline and Energy Transfer Crude Oil Pipeline. Source: RBN

DAPL was a lifesaver for crude oil producers in western North Dakota and critical to the continued growth of the Bakken shale play. Without DAPL, a second boom in Bakken production — from less than 1 MMb/d when the pipeline became operational to nearly 1.5 MMb/d at the play’s peak in late 2019 — may well not have occurred. But the COVID shock of early 2020 and other, related factors took the wind out of the Bakken’s sails. By May 2020, production had slipped to less than 900 Mb/d, and though output rebounded later in 2020 and over the next couple of years, the Bakken’s crude output has remained largely rangebound between 1.1 MMb/d and 1.2 MMb/d — well below the late-2019 high mark.

It ain't over, til it's over. And then it still ain't over. 

My hunch: this story won't be over until the DAPL is dead.

The Market -- Waiting For Godot -- September 20, 2023

Locator: 45512INV.

F / GM: both in the green, pre-market despite what appears to be a "red" day overall. Although "that' could change; market is now "green."

JPow: will talk tough; will hold rates steady. [Later: exactly what happened. It gets tedious. Traders loved it. Volatility is back.] [Later: and now, TWSJ suggesting the same thing: one more rate hike this year unlikely.]

Recession obsession: GDPNow at 4.9%.

Apple: after years of negative analysis because too much reliance on phones, mainstream analysts have a new strawman: the cloud.

  • analysts suggest Amazon has the "hold" on cloud computing;
  • analysts have forgotten what the cloud runs on

Recession? A reader brought this to my attention -- Dollar General is generally associated with doing well during recessions and hard time. The question: who is eating DG's lunch?


Apple: I'm inappropriately bullish on Apple; I'm the original Fanboy #3. That can be fact-checked but it's true. 

Generally speaking, reviews of new Apple releases / upgrades are generally panned by analysts but the Apple iPhone 15 is a real exception. Getting nothing but rave reviews. Wait times for deliveries already pushed out to the "holidays." Of the four models, three saw no price increases and the high end "15" with a modest increase in price appears to be the "one" folks want. They will let their carrier subsidize the cost. I expect to see price cuts on all four models by Christmas. And speaking of great reviews, here's another one.

Disclaimer: this is not an investment site.  Do not make any investment, financial, job, career, travel, or relationship decisions based on what you read here or think you may have read here. 

All my posts are done quickly: there will be content and typographical errors. If anything on any of my posts is important to you, go to the source. If/when I find typographical / content errors, I will correct them.  

Again, all my posts are done quickly. There will be typographical and content errors in all my posts. If any of my posts are important to you, go to the source.

Covid variants: in rapid succession, this summer -- the Eris, the Pi, and the Pirola variants. The most recent variant with 30 mutations on the genes coding for the surface "spike."

Pet Peeve -- Nothing To Do With The Bakken -- September 20, 2023

Locator: 45511INV.

Yesterday in passing in an e-mail sidebar, Dell Technologies came up in discussion.

It was my opportunity to vent.

One of my many pet peeves: the attention BRK gets.

As an investor, I only "compare" five-year histories:


Bakken And DAPL -- RBN Energy -- September 20, 2023

Locator: 45510B.

BRK: 53% in one sector. Incredibly "bad" article considering source.

INTC: excess data center chip inventories. Barron's.

********************************
Back to the Bakken

WTI: $90.64.

Thursday, September 21, 2023: 102 for the month; 304 for the quarter, 549 for the year
39621, conf, Crescent Point Enery, CPEUSC Farthing 2 30-31-158N-100W-MBH,
39556, conf, CLR, Fuller 9-2H1,
38034, conf, Petroshale, Tahu 3TFH,

Wednesday, September 20, 2023: 99 for the month; 301 for the quarter, 546 for the year
39557, conf, CLR, Fuller 10-2H,
37262, conf, Whiting, Wilson Federal 31-15H,

RBN Energy: new developments in Bakken crude oil production and DAPL. Archived.

A draft environmental impact statement (DEIS) tied to a key water crossing along the Dakota Access Pipeline (DAPL) has finally been completed and made public, thereby ending another chapter in the long-running drama about the ultimate fate of DAPL, which is by far the largest crude oil pipeline out of the Bakken. While the DEIS doesn’t finish the story, the document provides hints about possible outcomes — and an opportunity to review just how important the 750-Mb/d pipeline really is to Bakken producers and shippers. In today’s RBN blog, we discuss the latest developments regarding DAPL and Bakken production.