Showing posts sorted by date for query COP dividend. Sort by relevance Show all posts

Tuesday, August 18, 2026

Cramer's First Hour -- August 18, 2026

Locator: 51446CRAMER  

 ****************************
Half-Time Report

WTI: $85.57. 

Bonds: the amount of time these talking head spend on bonds is quite amazing, and not once do they mention great alternatives like EPD, ENB, CVX, PSC, COP, etc. or the top ten holdings in SCHD: ABT, AMGN, MRK, KO, HD, UNH, CVX, VZ, PG, and COP. 

Vaneck Semiconductor (SMH): is the action taking place today, profit taking that may only be a 72-hour blip, or is the semiconductor sector resetting for the rest of the year, or even longer? In other words, if you want to invest in semiconductors is the window of opportunity very short, or do you have plenty of time?

Investing then and investing now: in the old days, I could buy 100 shares of XYZ for $1,000. Now I can buy one, two, or three shares of SEMI. 

A trusted analyst: with regard to META, she is not at all concerned with the California trial starting today. If you are concerned, she says replace some/most/all META with AMZN. AMZN has a market cap of almost 3x META but whereas AMZN pays no dividend, META pays about 0.3%. 

***************************
Cramer's First Hour 

WTI: at $85.17. 

Jim Cramer continues to second quess the president on the Strait of Hormuz / Iran War

  • he admits he is not the president (well, that's good)
  • he knows not much more than what the rest of us know
  • he most likely knows less than what the chatbots know
  • he's completely missing the bigger story: how things have changed worldwide 
  • the US is the big winner on so many levels
  • at a minimum, we are rebuilding our arms stockpile 

Apple opened higher; still positive but off its highs.

JNJ: leading the Dow; up $6; treading at $268 (a defensive stock) 

Robots: link here. 

*********************************
Disclaimer

Briefly: 

  • I am inappropriately exuberant about the Bakken and I am often well out front of my headlights. I am often appropriately accused of hyperbole when it comes to the Bakken.
  • I am inappropriately exuberant about the US economy and the US market.
  • I am also inappropriately exuberant about all things Apple.
  • See disclaimer. This is not an investment site. 
  • Disclaimer: this is not an investment site. Do not make any investment, financial, job, career, travel, or relationship decisions based on what you read here or think you may have read here. All my posts are done quickly: there will be content and typographical errors. If something appears wrong, it probably is. Feel free to fact check everything.
  • If anything on any of my posts is important to you, go to the source. If/when I find typographical / content errors, I will correct them. 
  • Reminder: I am inappropriately exuberant about the Bakken, US economy, and the US market.
  • I am also inappropriately exuberant about all things Apple. 
  • And now, Nvidia, also. I am also inappropriately exuberant about all things Nvidia. Nvidia is a metonym for AI and/or the sixth industrial revolution. 
  • I've now added Broadcom to the disclaimer. I am also inappropriately exuberant about all things Broadcom. Now, I've added Amazon. And QCOM.
  • Longer version here.  
  • Monday, August 17, 2026

    Some Are Hitting New Highs -- If Not Very Close -- August 17, 2026

    Locator: 51436OIL.

    Tag: CVX PSX COP VNOM Energy Breakout  

    Meanwhile, BRK-B falls > 1% -- twice as much as what the S&P 500 fell (0.5%). And, of course, has never paid a dividend. Not too long ago, some analysts said BRK's oil holdings would be huge deal for BRK.


    Wednesday, December 10, 2025

    Fed Day -- December 10, 2025

    Locator: 49676THEFED. 

    Updates

    December 11, 2025: Cramer -- it's a green light to buy stocks from now to the end of the year. Tells investors to quit talking about the "next Fed vote." Analyze yesterday's "Fed cut": we're still in a period of easy money. Can't disagree. See graphic below the fold, Fed rate history.

    December 11, 2025: Forbes daily -- "the Fed cut" -- "third time's a charm. 

    Original Post  

    Sphinx .... Oracle of Delphi ... Oracle of Omaha .... the Fed.  

    Productivity has been rising at about 2% for "decades" per Fed chairman.

    Fact check:

    Disinflation is being seen in the services industry. Services accounts for two-thirds of the US economy. 

    Dow: up significantly after the Fed chairman's comments, after cutting 25 basis points -- up 460 points, not over 48,000. Trending in such a way that the Dow could rise more than 500 points before the close. And it did, now up over 525 points.

    S&P 500: up 47 points -- trading at 6,888.

    NASDAQ: up 83 points -- trading at 23,660.  

    If this is not a Santa Claus rally, I do not know what is. 

    ***************************
    BRK

    On a day that the Fed cuts rates and the Dow surges, as well as the S&P 500 and the NASDAQ, for all practical purposes, BRK-B is down again.

    Up seven cents / share on a day the markets surge. Including energy -- with one huge exception -- natural gas carriers (OKE, LNG, and VG). WMB is down almost 2%. SRE is up very slightly. ENB is down more than 1% and EPD is down a quarter percent. Meanwhile the oils / integrated are doing great, each up about 2% (CVX, COP, PSX). Valero and MPC are up 1% and half-a-percent, respectively. OKLO is down 2% -- this certainly seems to comfort those who are worried about energy costs for AI infrrastructure. 

    AAPL is up about 3/4ths of a percent, over $2 / share. AVGO is up another 1.25% while ORCL is flat. Oracle reports after the close today.

    Both Chubb and BRK-B were down today. Chubb was down over 1.5% (down almost $5/share) and BRK-B was down $1/share, back down to $490. I'm so glad I spent three hours with ChatGPT discussing BRK, Chubb, and global insurance. After that discussion it all makes sense why BRK, Chubb, and insurance companies in general would be down today. 

    UNP, a proxy for BNSF, was up over 1.5% (up $3.90/share today) and AAPL was up half-a-percent, up $1.60/share.  

    The GE Vernova story is telling. GE Vernova's share price jumped 15% after CEO's remarks today, and the doubling of the dividend. Did you catch that: GE Vernova double its dividend.

    GE Vernova is all about natural gas powering AI.  

    I was curious so I asked Charlie:

    AI prompt: 

    Back to powering AI data centers, etc. GE Vernova is all about powering AI data centers with a focus on natural gas right now and looking to nuclear later. Against that data point, BRK is probably one of the largest power (electricity) suppliers in the US, and is huge into natural gas properties (think OXY). In some ways, BRK is #1 in insurance but is very, very will situated for supplying electricity to the AI buildout. So what gives? How can GE Vernova double its dividend and see its share price JUMP 15% IN ONE DAY! What gives? Where does BRK stand with regard to GE Vernova and its involvement with the AI buildout? Where is BRK with all its energy holdings compared to well-known power companies like NextEra Energy and Duke, etc.

    Extremely interesting. Almost comparing apples to oranges. I didn't ask Charlie where he would put his/her/its money if he/she/it were an investor, but my takeaway is this:

    • for me, I'm not starting any new position in any ticker without selling something else (I can only track so much);
    • BRK is a stead-Eddy and remains a solid, steady investment for me as much as I am disappointed in what Berkshire is doing now; and,
    • validate my feelings that AI is not a bubble (when GE Vernova jumps 15% in one day), and invest accordingly.

    Charlie really lays out the BRK story versus the GE Vernova story very, very well. Makes me feel very, very comfortable with BRK. 

    On a completely different note, when one sees "a GE Vernova" double its dividend and sees its shares jump 15% in one day, one can be very disappointed / discouraged not to have "a GE Vernova" in one's portfolio when one was aware of the opportunity six months ago. 

    But, when I look at my overall portfolio and what I've been doing, I'm reminded that I should be quite happy. It's been an incredible year, but more importantly, it's been an incredible 30 years. No regrets. Some "what-ifs" but I try very, very hard to ignore "what-ifs" and simply move on.

    Thursday, November 6, 2025

    COP Raises Dividend 8% On Great Earnings, Guidance -- November 6, 2025

    Locator: 49354B.

    COP: beats on earnings; raises output forecast; and, raises dividend.

    ******************************
    Back to the Bakken

    WTI: $60.01. Link here.

    New wells: link here.

    RBN Energy: link here.

    Thursday, August 7, 2025

    Liberation Day: August 7, 2025 -- Trump Demands That INTC CEO Resign Immediately -- Chinese Connection Not Tenable -- INTC Falling Over 4% Pre-Market -- August 7, 2025

    Locator: 48793LD.

    Stock to watch today: SRE.  

    LNG earnings. Link here.

    Cramer hour:

    • top story: Samsung, then Corning!
    • Apple American Manufacturing Program: how the "supply chain" starts
    • Apple Silicon supply chain, end-to-end
    • $600 billion over four years -- but doesn't really increase Apple's CAPEX all that much
    • the pre-market tech stocks are surging

    COP: sells Anadarko Basin assets. Anadarko is tracked here. Next: CVX to sell Bakken assets (tea leaves only, not announced).

    • could we see Hess back in North Dakota? Here's hoping.
    • North Dakota is Hess!
    • from ChatGPT:

    Jobless claims and productivity data: for what they're worth --

    • non-farm 2Q24 productivity: better than expected, 2.4% vs 2.0%
    • initial jobless claims: 226 vs 221k expected; "very well behaved"
    • unit labor costs: 1.6% vs 1.5% estimate
    • these numbers won't derail today's market; numbers, "generically pretty good."
    • Steve Liesman:
      • says productivity numbers are a "bit squirrely" 
      • finally, finally, finally -- this is huge -- unemployment numbers greatly affected by AI.
      • see my note two days ago, August 5, 2025 -- Steve must be reading the blog. LOL.

    Scott Kupor: OPM Director, Stanford Graduate School of Business. 

    Does Trump ever sleep? Demands Intel CEO step down. Having said that, 

    • US Congress -- glacial in getting anything done even when in session
    • a single member can use parliamentary rules to bring all work to a halt
      • or just hand it off to Judge Boasberg
      • other than government, does anyone use parliamentary rules (oh, yeah, that big island north of Europe)
    • members can't get out of Washington fast enough on Fridays
    • long holiday breaks
    • end of confirmation of Trump's picks; big political story; doesn't matter

    INTC: misstep after misstep after misstep --


    DFW: keeps announcing new routes. Most recent: Cathay Pacific non-stop DFW to Hong Kong.

    SRE earnings: just released; company's PR release --

    • Pre-market, SRE: unchanged.

    Best interview so far today -- 6:45 a.m. CT: Walter Isaacson on CNBC
    coincidentally, a copy of Walter Isaacson's book next to my laptop (photo not staged -- LOL)

    Liberation Day:

    • the "original liberation" day, political, April, 2, 2027, wiki.
    • Apple's / America's tech: liberation day -- August 7, 2025. Link here.

    ***************************
    What We'll Be Talking About Today


    INTC

    • Trump has just tweeted -- INTC CEO must resign immediately -- Lip-Bu Tan -- China Ties!
    • INTC down 3.5% in pre-market trading; now down 4.26%

    Market

    • Bank of England cuts interest rates by a quarter point

    Market

    • after yesterday's surge, US equity markets could break new records at open

    Market

    • Northup-backed aerospace company IPO today: Firefly Aerospace; IPO priced at $45.
    • Warner Bros Discovery: beat on top and bottom. 

    Apple

    • sold its 3 billionth iPhone last quarter -- that's a lot of Corning glass; link here.
    • GLW surges 3.5% in pre-market trading

    Geo-politics:

    • Trump and Putin may meet very soon
    "Liberation Day" -- American tech
    • American tech explosion, particularly Texas, Samsung, Intel
    • Apple partners with Samsung on new chip
    • American Manufacturing Program

    Earnings out pre-market:

    • COP
      • beats by six cents
      • COP up almost 2% pre-market; up $1.79 / share;
      • non-GAAP: $1.42
      • midpoint of FY output guidance unchanged
      • maintains dividend at 78 cents / share
    • SRE

    AI tool: trickle. Incredibly interesting: https://content.trickle.so/tools. 

    Germany: chart of the day. Link here.


    **********************
    From Earlier

    Then this:

    Add: GLW.

    Then review:

    American Manufacturing Company (did he ad-lib this name? LOL!)
    • Apple
    • Samsung
    • Corning
    • Coherent
    • GlobalWavers
    • Applied Materials
    • Texas Instruments
    • GlobalFoundries
    • Amkor
    • Broadcom

    Note which company is not on that list: TSMC.

    Old, haven't seen an update recently:

    **********************************
    Disclaimer
    Brief Reminder 

    Briefly:

    • I am inappropriately exuberant about the Bakken and I am often well out front of my headlights. I am often appropriately accused of hyperbole when it comes to the Bakken.
    • I am inappropriately exuberant about the US economy and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • See disclaimer. This is not an investment site. 
    • Disclaimer: this is not an investment site. Do not make any investment, financial, job, career, travel, or relationship decisions based on what you read here or think you may have read here. All my posts are done quickly: there will be content and typographical errors. If something appears wrong, it probably is. Feel free to fact check everything.
    • If anything on any of my posts is important to you, go to the source. If/when I find typographical / content errors, I will correct them. 
    • Reminder: I am inappropriately exuberant about the Bakken, US economy, and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • And now, Nvidia, also. I am also inappropriately exuberant about all things Nvidia. Nvidia is a metonym for AI and/or the sixth industrial revolution.
    • I've now added Broadcom to the disclaimer. I am also inappropriately exuberant about all things Broadcom.
    • Longer version here.   

    Wednesday, July 23, 2025

    What We Will Be Talking About Mid-Week -- July 23, 2025

    Locator: 48805HEADLINES.

    Ticker CHRD: the record date for the August dividend payment for Chord Energy is August 15, 2025. This means shareholders of record on this date will be eligible to receive the August dividend. The dividend will likely be declared on or around August 2, 2025. The payment date is scheduled for August 29, 2025.

    Tesla: California registrations down 20% in 2Q25.

    Apple: looks like EU will accept Apple's proposals. Huge. Two words: President Trump.

    EPA: about to "86" climate change? By the way: etiology of the "86" is completely unknown. However,

    The slang term "86" generally means to get rid of, refuse service to, or eliminate something or someone. While its precise origin is debated, it's widely believed to have originated in the restaurant and bar industry in the early 20th century, possibly as a form of code or shorthand.
    "Possibly as a form of code or shorthand." Well, duh.

    Lake Mead: record low. Link here.

    BRK: folks are starting to take notice. Neither article says much; social media comments are helpful. Even huge apologists for WB / BRK can read these numbers.

    "Inching"? LOL. Pre-market, July 23, 2025, just after Trump announces trade deal with Japan.


    Permian update: without question, a must-read, one of the best Julianne Geiger articles on the subject ... or maybe it's just because it's such a "feel-good" article. Link here.

     
    Some excerpts but every paragraph is worth reading:

    WoodMac expects ExxonMobil’s Permian output to rise 55% to 2.3 million boe/d by decade’s end, holding steady through 2040. Chevron is expected to churn out a 25% increase, to 1.2 million boe/d by 2030. In both cases, the Permian will supply nearly a third of total output—onshore, low-cost, and infrastructure-rich. It's not just scale—it’s resilience. Even as the broader U.S. rig count drops (down 7 last week alone, to 544), these majors are using AI and advanced analytics to keep well costs low and recovery factors trending up.

    Goldman Sachs recently declared the U.S. shale boom years officially over. But that misses the nuance. Yes, the easy growth is gone. But for majors with prime Tier 1 acreage and deep capital pools, this isn’t the end—it’s the monetization phase. 

    The focus now is on harvesting cash, not chasing barrels. What makes the Permian such a strategic fortress isn’t just its size—it’s the rare combination of geology, infrastructure, and optionality. With thousands of drilled-but-uncompleted wells, ample takeaway capacity, and unmatched midstream connectivity, operators can toggle activity up or down faster than anywhere else on earth. That responsiveness gives U.S. majors a tactical edge in volatile markets. And as capital discipline replaces boom-era exuberance, it’s the companies with scale and flexibility that will win.

    The Permian isn’t just a resource—it’s a lever for navigating the next two decades of uncertainty, and Exxon and Chevron are the only ones strong enough to pull it with confidence.

    COP / Oklahoma / Anadarko shale: link here.  Also, here, no paywall yet. Stone Ridge Energy to acquire; Flywheel Energy to operate.

    The sale, if completed, would enable ConocoPhillips to exceed its divestment goal of $2bn, a target established following the assumption of $5.4bn in debt from Marathon.

    • The numbers (it looks like a great deal for both companies):
      • $1.3 billion
      • 300,000 acres
      • 39,000 boepd
      • per acre: $4,333 / acre
      • per flowing boe: $33,333

    The grid: link here. Even better, much more data and no paywall yet. Archived. This was major headline story over on CNBC at 5:31 a.m. CT. Again this was an all-time record.

    Not only did rates go up, but production will increase -- higher rates, increased generation:

    These are incredible numbers:

    PJM auction prices rise due to data center demand, supply shortfall, per MW: $329 / 270 = 22% increase. For BGE and Dominion: $466 / $444, respectively. 
    PJM Interconnection today announced the results of its 2026/2027 Base Residual Auction (BRA), which secured 134,311 MW of unforced capacity generation (UCAP) and demand response to meet projected electricity needs for more than 67 million people across 13 states and the District of Columbia.
    Regions under the Fixed Resource Requirement acquired an additional 11,933 MW in UCAP for a total of 146,244 MW (UCAP) available to serve forecasted peak electricity demand plus a reserve margin.
    UCAP represents a generation resource’s maximum output adjusted for its estimated ability to reliably perform at times of highest system risk. The price came in at the FERC-approved cap, $329.17/MW-day (UCAP), for the entire PJM footprint. This price compares with $269.92/MW-day for the 2025/2026 auction for the RTO, except for the BGE and Dominion zones, which cleared at $466.35/MW-day and $444.26/MW-day, respectively.

    **********************************
    Disclaimer
    Brief Reminder 

    Briefly:

    • I am inappropriately exuberant about the Bakken and I am often well out front of my headlights. I am often appropriately accused of hyperbole when it comes to the Bakken.
    • I am inappropriately exuberant about the US economy and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • See disclaimer. This is not an investment site. 
    • Disclaimer: this is not an investment site. Do not make any investment, financial, job, career, travel, or relationship decisions based on what you read here or think you may have read here. All my posts are done quickly: there will be content and typographical errors. If something appears wrong, it probably is. Feel free to fact check everything.
    • If anything on any of my posts is important to you, go to the source. If/when I find typographical / content errors, I will correct them. 
    • Reminder: I am inappropriately exuberant about the Bakken, US economy, and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • And now, Nvidia, also. I am also inappropriately exuberant about all things Nvidia. Nvidia is a metonym for AI and/or the sixth industrial revolution.
    • I've now added Broadcom to the disclaimer. I am also inappropriately exuberant about all things Broadcom.
    • Longer version here.   

    Wednesday, June 4, 2025

    This Is Not An Investment Site -- This Information Is Posted To Put The Bakken In Perspective -- June42, 2025

    Locator: 48677B.

    Breaking, jobs report: May ADP employment report -- jobs added in private sector --  37K vs 110K estimate. 

    Certainly this will get the attention of the Fed's JPow, but JPow will stay the course; will not react politically; will make decisions based on data and generally ignore Trump just because he can. Tea leaves: both inflation and unemployment will trend higher over the summer. Before the jobs report, Dow futures were up almost 100 points; after the jobs report, Dow futures are up only 35 points. The Dow is likely to open in the red.

    From April 22, 2025: North Dakota strengths --

    Drones: the U.S. Air Force (USAF) has a significant presence in North Dakota, particularly at Grand Forks Air Force Base, which serves as a hub for unmanned aerial systems (UAS) research, development, and operations. North Dakota is also home to GrandSKY, the nation's first drone business park co-located on an active Air Force base, further solidifying its position as a drone innovation center.

    Strategic: The USAF B-52 Stratofortress bomber is primarily stationed at Minot AFB, North Dakota and Barksdale AFB, Louisiana. These are the main bases where the B-52 is operated by the Air Force Global Strike Command and the Air Force Reserve Command. Additionally, a significant number of B-52s are stored in long-term storage at Davis-Monthan AFB's Boneyard.


    Futures:

    Let me guess: the #1 story on CNBC today -- talking about the Fed.

    The blog: the only blog focusing on the Bakken that has no requirement for subscriptions, no ads, no passwords, or paywalls. Did I forget anything? The blog is posted for my own use and immediate family members. Others are welcome to read it but I don't recommend that anyone read it except perhaps for entertainment purposes.

    Page views: since inception, we start the day, June 4, 2025, 5:23 a.m. with 21,447,091 page views. The blog has been up and running for 5,817 days. According to ChatGPT:

    The Million Dollar Way blog, which focuses on the Bakken oil industry, has been active since at least June 2009. This is evidenced by discussions about the blog’s status on forums as early as June 2009. As of June 4, 2025, this indicates that the blog has been posting for approximately 5,817 days.

    Before I forget: a reader writes me -- for mineral owners -- huge, huge advice -- take advantage of EnergyLink for tracking personal minerals. 

    No link although easy to find; maybe I'll post link later, but reader says most (if not all) operators in the Bakken provide a notice each month by mail to every mineral owner how to enroll with EnergyLink. I assume they do this for all US operators, not just those operating in the Bakken.

    Two books I'm reading today:

    • The Story of Semiconductors, John Orton, Oxford Press, c. 2004.
    • The Perfectionists: How Precision Engineers Created The Modern World, Simo Winchester, c. 2018.

    On order:

    • The Innovators: How A Group of Hackers, Geniuses, and Geeks Created the Digital Revolution, Walter Isaacson, c. 2015. 

    ***************************************

    Disclaimer
    Brief Reminder 

     Briefly:

    • I am inappropriately exuberant about the Bakken and I am often well out front of my headlights. I am often appropriately accused of hyperbole when it comes to the Bakken.
    • I am inappropriately exuberant about the US economy and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • See disclaimer. This is not an investment site. 
    • Disclaimer: this is not an investment site. Do not make any investment, financial, job, career, travel, or relationship decisions based on what you read here or think you may have read here. All my posts are done quickly: there will be content and typographical errors. If something appears wrong, it probably is. Feel free to fact check everything.
    • If anything on any of my posts is important to you, go to the source. If/when I find typographical / content errors, I will correct them. 
    • Reminder: I am inappropriately exuberant about the Bakken, US economy, and the US market.
    • I am also inappropriately exuberant about all things Apple. 
    • And now, Nvidia, also. I am also inappropriately exuberant about all things Nvidia. Nvidia is a metonym for AI and/or the sixth industrial revolution.
    • I've now added Broadcom to the disclaimer. I am also inappropriately exuberant about all things Broadcom.
    • I've now added Oracle to the disclaimer. I am also inappropriately exuberant about all things Oracle.
    • Longer version here.  

     *********************************
    Bullets

    Quick notes. I may get back to some of these later today. But probably not. Going swimming, bike riding.

    • I can't stress enough how invaluable X has been for the blog, for personal investing
      • my feed gets "almost zero" political tweets
      • one has to be very, very selective when it comes to whom one follows
    • ChatGPT is incredible; I almost feel guilty relying on it as much as I do
    • geo-politics, in no particular order; stream of consciousness.
      • Iran defies Trump; will continue enriching nuclear fuel
      • the US will rue the day when "we" did not end once-and-for-all Russia's war with Ukraine, Iran's nuclear program when "we" had a once-in-a-lifetime opportunity to do in 2025
        • Israel and the US are in a standoff with regard to whether to strike Iran's nuclear facilities
        • Iran's latest defiance may bring the Israel - US standoff to an end
        • the incredible Ukraine strike on Russia may influence the outcome of the Israel - US standoff
      • Ukraine-Russia
        • can you imagine the response in this country had a terrorist cell in Canada managed to do to America's B-52 bases what Ukraine did to Russia's strategic bomber fleet
        • Russia no longer produces strategic bombers, has not done do for decades, and no longer has the capacity to build new strategic bombers or replace the ones they lost
    • whoo-hoo! FANG subsidiary Viper Energy will buy the assets of STR (Sitio Resources); over at oilprice --
      • one of my best investments ever; long story; but directly as a result of X
      • difficult to find "full" story; ChatGPT was the solution (again)
    • AVGO (Broadcom) is all over the news lately; links below; also one of my best investments ever; huge thanks to a reader who brought AVGO to my attention several years ago
    • ONEOK buys remaining stake in Delaware Basisn JV for just one one billion dollars; breaking on Reuters (paywall);g ChatGPT provides "whole" story.
    • Texas pension fund had boycott on Blackrock (ESG); Texas has lifted that boycott; now invests in BlackRock; link here. 
      • debate between Anas and Giovanni -- let's see what ChatGPT has to say about this. Simple question: why was BlackRock removed from Texas boycott? Giovanni is/was correct.
    • Trump: like him or hate him, he knows what he's doing and he's not waiting around
      • US non-fuel trade deficit soars; fuel trade turns to surplus. Amazing story. Wasn't even a story until Trump got involved; most activist president since FDR; finally some adulting in the room.
    • Constellation - Meta: can one think of a bigger energy story; the day ESG died; link here. For someone who comes across as a bozo, he has really come a long, long way; is he a better CEO than Tim Cook? Over at X. SIR.
    • Deportation / immigration: new "top cop" for Dallas, TX -- Dallas is no longer a sanctuary city. Let that sink in for a few minutes. Dallas is as blue as it gets when it comes to politics.
    • America's wealth and the multi-millionaires next door; link here. 
    • Nine of these companies have a market cap of over $1 trillion -- though one is likely to fall off that list at least sometime this year;
      • Walmart at $800 is #10; long way to go to get to $1 trillion
      • BRK losing its Warren Buffett patina; story at Barron's.  Patina: a gloss or sheen on a surface resulting from age of polishing; Buffett "guilty" of both.
      • three of the top 30 largest stocks (by market cap) in the world hit new all-time highs yesterday; link here; Broadcom (AVG); Netflix (NFLX); and Palantir (PLTR).

    Screenshots from some of the links above.


    Not to be forgotten:

    Measles vaccination rates, US, link here. Thank you RFK, Jr.

    California refineries:

    California's oil refining sector is experiencing significant changes, including the potential closure of two major refineries, which is raising concerns about fuel supply and prices. The Phillips 66 Los Angeles refinery is scheduled to close in late 2025, and the Valero Benicia refinery is expected to shut down in April 2026. These closures could lead to a shortage in California's fuel supply and potentially increase gasoline prices. So, even if a source for additional heavy oil is found, it won't be particularly helpful to California if these refineries shut down as scheduled.

    CVX: 5-day ticker, pays almost 5%; for long-term investors, pays a whole lot more than 5%. 

    P/E of 16; P/E similar to XOM and OXY.  With the pay date of March 10, 2025, CVX increased its quarterly dividend from $1.63 to $1.71, a 4.9% increase.

    Only three states where nightly hotel rates are not tracked: North Dakota, Alaska and Hawaii. Link here.

    I can't make this stuff up. Posted one hour ago. Link here.  Meanwhile, three weeks ago, Governor Newsom committed another "massive" amount of state funding for the bullet train. Link here.

    ***************************
    Back to the Bakken

    WTI: $63.63.

    New wells:

    • Thursday, June 5, 2025: 21 for the month, 174 for the quarter, 388 for the year,
      • None.
    • Wednesday, June 4, 2025: 21 for the month, 174 for the quarter, 388 for the year,
      • 41312, conf, CLR, Helen 7-8H,
      • 40795, conf, St Croix Operating, St Croix Antler 1,

    RBN Energy: Chevron's diminished role in Venezuela complicates plans for US refiners seeking heavy crude. Archived.

    Exports of Venezuelan crude to the U.S. have moved lower in recent months, a trend that seems likely to continue with the May 27 expiration of Chevron’s permit to operate there. But while a limited extension of that permit appears likely, if not yet official, the development adds new challenges for Gulf Coast refiners that process heavy crude. In today’s RBN blog, we’ll update the situation in Venezuela, assess what it means for Chevron, and discuss the outlook for the heavy crude-capable Gulf Coast refiners. 

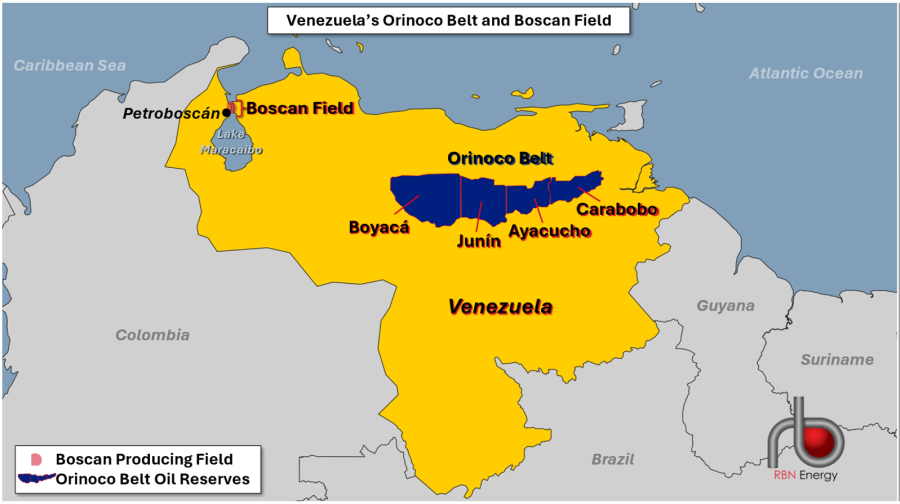
    Let’s start with some background on Chevron’s long history in Venezuela, which dates back more than 100 years. Chevron’s legacy company, Venezuelan Gulf Oil, began drilling in 1924, spurring commercial oil production there, and followed that up with operations at Lake Maracaibo and the Boscan Field (tiny, pink-shaded area in Figure 1 below) in northwestern Venezuela. Then-President Carlos Andrés Pérez nationalized Venezuela’s oil industry in 1976 and established Petróleos de Venezuela S.A. (PDVSA) as the state-owned oil company, but despite the nationalization, Chevron remained, and it was asked to form joint ventures (JVs) with PDVSA. In 2006-07, then-President Hugo Chávez’s regime increased royalties and taxes on foreign oil companies and made other changes that prompted some companies — including ExxonMobil and ConocoPhillips — to leave Venezuela.
    Venezuela’s Orinoco Belt and Boscan Field

    Figure 1. Venezuela’s Orinoco Belt and Boscan Field. Source: RBN

    But Chevron hung on, attracted by Venezuela’s vast reserves and the ability to profitably produce oil at relatively low costs. By staying put, Chevron agreed to give up majority control of its operations to PDVSA. Still, it retained 40% interests and continued to be involved in several onshore and offshore projects, including Petroboscán in western Venezuela, while focusing on extra-heavy oil production in three blocks within the Carabobo area of the Orinoco Belt (blue-shaded area in Figure 1 above).

    There have been other ups and downs for Chevron along the way, resulting in a mostly downward trend for Venezuelan crude exports to the U.S. in recent years (see Figure 2 below). The first Trump administration imposed economic sanctions on Venezuela in August 2017, which resulted in lower oil production and reduced exports to the U.S. The Trump administration followed that up with an April 2020 order for Chevron to wind down production in Venezuela, although exports to the U.S. had reached zero by that time. The Biden administration later reversed that order and eased sanctions further in October 2022, allowing Chevron to increase production for sales to the U.S. Imports began again in January 2023.

    *****************************
    Uinta -- Re-Posting

    RBN Energy: Supreme Court's ruling on Uinta Basin railway is a big win for energy infrastructure projects. Archived.

    Midstream developers have complained for decades that federal courts reviewing agency approvals for their infrastructure projects have cast too wide a net — that is, instead of requiring agencies to simply analyze the specific environmental impacts of the project in question, the courts have been insisting regulators also examine the effects of the upstream and downstream activities the project would enable. As we discuss in today’s RBN blog, the U.S. Supreme Court ruled last week that under the all-important National Environmental Policy Act (NEPA) of 1969, it’s up to regulators to set the boundaries of their environmental review and that courts should defer to their judgment as long as they fall within a “broad zone of reasonableness.”

    Also, two other related posts. 

    First, earlier on the blog:

    Uinta Basin Railway: finally, some adulting in the room. And it was unanimous. Link here. Also, reported in The New York Times. This has to be a big story if it's being reported by TNYT.

    The U.S. Supreme Court has given the green light to Utah’s Uinta Basin Railway project, backing a narrower interpretation of environmental review laws and potentially clearing the path for a major expansion in oil transport capacity.

    In a unanimous decision Thursday, the justices reversed a lower court ruling, slamming it for what they described as an overly expansive and intrusive interpretation of environmental law. The line would link the Uinta Basin’s oil fields—tucked deep in northeastern Utah’s sagebrush terrain—to the national rail network, unlocking access to Gulf Coast and West Coast refineries.

    At the heart of the case was how far federal agencies must go under the National Environmental Policy Act (NEPA) to evaluate ripple effects—like emissions from oil refining or increased drilling—when considering infrastructure projects.
    Writing for the court, Justice Brett Kavanaugh affirmed that federal agencies have discretion to weigh environmental impacts as they see fit, pushing back on calls for broader reviews that include downstream effects like refining emissions or increased oil consumption.

    “Simply stated, NEPA is a procedural cross-check, not a substantive roadblock. The goal of the law is to inform agency decision-making, not to paralyze it,” Justice Kavanaugh said in the ruling.

    Second, another RBN Energy blog, posted a few days ago:

    A reminder, the full story below has been released and will be available for a short period of time. This story has much more than the subject heading would indicate. An important read:

    RBN Energy: the short- and long-term outlooks for Uinta waxy crude production. Archived.

    We’ve discussed the qualities of the Uinta Basin’s unusual waxy crude, the challenges inherent in moving it to market, and the use of machine-learning AI to optimize its extraction from two key geologic layers or “benches” deep below the rugged hills of northeastern Utah. Now, in today’s RBN blog, it’s finally time to reveal what all this tells us regarding the prospects for continued Uinta production growth; the need for new takeaway capacity, blending and refining infrastructure to handle it; and — very important — the estimated duration of economically recoverable waxy crude under various price scenarios. 

    This is the third blog in our series on how artificial intelligence (AI) is being used to assess and optimize the development potential of the Uinta Basin, which is now the fastest-growing crude-oil-focused production area in the U.S. on a percentage basis. In Part 1, we discussed the two flavors of Uinta waxy crude (black wax and yellow wax); their positive attributes (great for making high-value lubricants, low levels of sulfur and other impurities, and desirable yields of gasoil, kerosene, naphtha and other essential refined products); and initial production (IP) rates that match — and in some cases exceed — those in the best parts of the Permian.

    We also described the challenges of storing and transporting waxy crude, the fast rise in Uinta production (now averaging more than 170 Mb/d), the demand from distant refineries and blenders, and the strain being put on existing midstream and downstream infrastructure. That’s all spurred talk of expansion projects, but E&Ps, rail terminal developers, refiners and blenders are wary of making big up-front investments without having a clear understanding of the Uinta’s long-term prospects and, with that, a high degree of confidence that the basin will remain economically productive long enough for their investments to pay off.

    In Part 2, we examined the AI-based analytics our friends at Novi Labs use to (1) understand the individual contributions of a wide range of geologic and operational variables to production levels in the Uinta’s two most extensively drilled benches (Uteland Butte and Castle Peak), (2) employ that understanding to predict the performance of future wells in the two benches, and (3) forecast the volumes of waxy crude that could ultimately be extracted from these benches at various price points. Put simply — well, as simply as we can — Novi Labs’ machine-learning approach begins by gathering and incorporating a broad range of well-specific inputs (geologic, operational and spatial) on hundreds of drilled wells from public and proprietary sources. Novi then leverages the algorithms in the models it developed for each of the two benches, using reams of available data to gain a much deeper understanding of the relationships among and between these many variables and their impact on production outcomes.

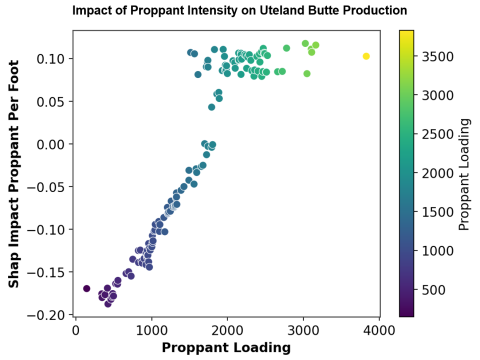
    In essence, machine learning integrates the wide range of data collected to recognize patterns and identify the primary drivers of well performance. It does this through the development and use of “Shapley values,” a game-theory concept that quantifies the contribution of individual input categories — more on that in a moment — to production from a given well compared to the average of the wells in the area. Machine learning then enables operators to assess how changing specific variables (such as drilling in a higher-pressure area, tightening well spacing, or increasing proppant intensity) would affect production outcomes in wells yet to be drilled. It also provides operators with guidance on how best to lay out, space, and sequence the development of the benches.

    Today, we’ll build on the discussion about machine learning and Shapley values, compare the Uinta’s forecast productivity per well to the Permian and Bakken, and look at how much crude the wells in the Uinta’s key benches are likely to produce over time at various price points.

    Novi Labs selected about 20 data points or variables (out of a broad set available to it) on hundreds of drilled wells in the Uteland Butte and Castle Peak benches that meet its criteria (at least 90 days of production and values for proppant, completion fluid and lateral length). The geologic data includes things like porosity, total organic carbon (TOC), lithology (the physical and chemical characteristics of the rock) and pressure, plus depth, structural position within the basin and proximity to faults. The operational data, in turn, includes factors such as proppant intensity, fluid volume per foot, stage spacing, lateral length, and the precise placement of the lateral within the bench.

    Impact of Proppant Intensity on Uteland Butte Production
    Impact of Proppant Intensity on Uteland Butte Production

    Figure 1. Impact of Proppant Intensity on Uteland Butte Production. Source: Novi Labs

    Thursday, March 27, 2025

    For Investors -- Natural Gas Companies -- March 28, 2025

    Locator: 48381B.

    Note blog's disclaimer before proceeding.

    Natural gas companies: ten best for investors, per Insider Monkey, link here. Perhaps here is better.
    In reverse order, #10 to #1:

    • Williams (WMB)
      • moves one-third of all natural gas in the US
      • price target raised from $61 to $62
    • Canadian Natural Resources Limited (CNQ)
    • Shell (SHEL)
      • price target, $82
    • Duke Energy Corporation (DUK)
      • price target $128, recently raised from $123
    • OXY
      • price target $59, recently raised from $52; "neutral" rating
    • Chevron Corporation (CVX)
      • share buybacks in 2024: $15 billion
    • Targa Resources Corp (TRGP)
    • ConocoPhillips (COP) 
      • price target of $137; currently $103
    • Exxon Mobil Corporation (XOM)
      • price target of $133;
    • Hess Corporation (HES)
      • often shows up in these sorts of lists; will likely be acquired by either XOM or HES;
      • EPS, 4Q24
        • $1.76, easily surpassing forecast of $1.53
      • cash flow, 4Q24:
        • $4.93 vs $4.29, estimated; pays $2.00 annual dividend

    OXY: Vanguard Group buys 10 million shares of OXY. Link here. Archived.

    CNBC's Cramer on OXY: no.

    ******************************
    Back to the Bakken

    WTI: $69.58.

    New wells:

    • Friday, March 28, 2025: 81 for the month, 192 for the quarter, 192 for the year,
      • 40512, conf, Phoenix Operating, Daniele 26-35 2 5H,
      • 40511, conf, Phoenix Operating, Daniele 26-35-2 4H,
      • 40510, conf, Phoenix Operating, Daniele 26-35-2 2H,
      • 40509, conf, Phoenix Operating, Daniele 26-35-2 1H-LL,
      • 40474, conf, Hess, GO-John-156-98-0508H-3,
      • 40447, conf, Phoenix Operating, Daniele 26-35-2 3H,
    • Thursday, March 27, 2025: 75 for the month, 190 for the quarter, 190 for the year,
      • 41073, conf, BR, Tilton Diamond Forest 2A ULW,
      • 40219, conf, Hunt, Halliday 146-92-18-1H 1,
      • 40218, conf, Hunt, Halliday 146-92-19-36H 1,
      • 39319, conf, Grayson Operating, Marilyn 31-33 3H,

    RBN Energy: gas producers drive 4Q24 earnings growth as oil prices languish. 

    Most conversations and analyses around hydrocarbon prices tend to focus on crude oil, if for no other reason than the direct exposure we experience when filling up at the pump. After the commodity price crash in early 2020, which threatened the financial stability of U.S. E&Ps, a subsequent surge in oil prices drove a remarkable recovery, winning back investor confidence in the industry. Crude realizations have subsequently declined, slowly but steadily eroding producer results. Fortunately, the outlook for natural gas, which represents just under half the total output of our 38 U.S. E&Ps, has begun to brighten. In today’s RBN blog, we analyze Q4 2024 results for the major E&Ps we cover with a focus on the impact of rising natural gas prices. 

    As shown in Figure 1 below, E&P pre-tax operating earnings (blue bars and left axis) rose to record highs in 2021 and 2022, then declined through 2023 and the first three quarters of 2024. 

    The driver was a drop in crude oil prices from more than $100/bbl in mid-2022 to a $70-$80/bbl range over the last eight quarters. The quarterly average price reached a three-year low of $70.32/bbl in Q4 2024. Despite the substantial dip from $75.26/bbl in Q3 2024, the erosion in profits stopped, as pre-tax income for our universe rose 1.5%, from $10.72/boe to $10.89/boe. Natural gas prices rose from record lows in the first three quarters of 2024, which kept Q4 2024 revenue essentially flat at $35.60/boe despite the 7% decline in average WTI prices.

      E&P Financial Results and Production, 2014-Q4 2024

    Figure 1. E&P Financial Results and Production, 2014-Q4 2024.

    Source: Oil & Gas Financial Analytics, LLC

    The Henry Hub spot price increased from $1.99/MMBtu in August 2024 to $3.01/MMBtu in December. As a result, average realized natural gas prices for major producers increased. For example, EOG’s quarter-over-quarter gas realizations rose by 41%, Devon Energy’s increased by 50% and ConocoPhillips’ jumped by 77%. Permian producers that faced negative pricing at the Waha Hub for long stretches in mid-2024 (see Don’t Blame Me) benefited from a turn to the positive, as Diamondback Energy’s average realization pivoted from a $0.26/MMBtu loss in Q3 2024 to an $0.82/MMBtu gain in Q4 2024.